MoodWallet: Money Management

Screenshots
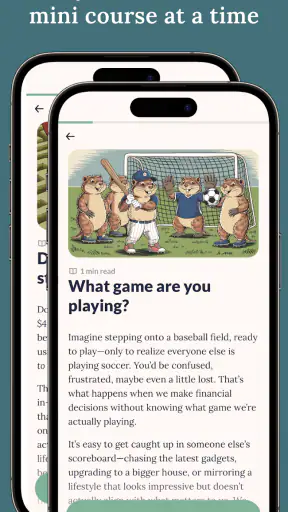
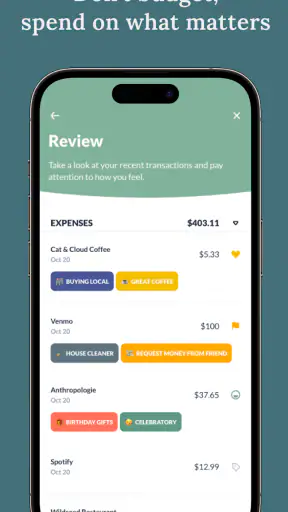
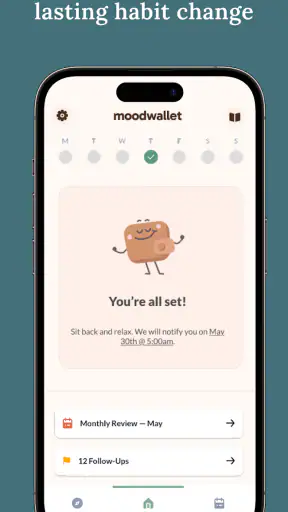
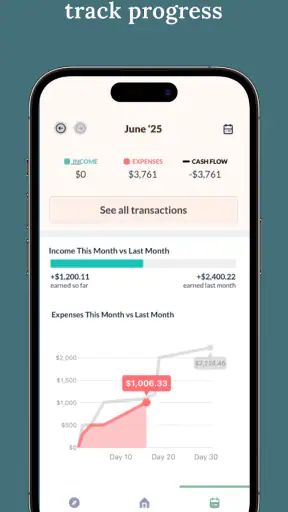
Details
- Rating
- 41.00 reviews
- Version
- 2.12.0
- Developer
- Jomo Labs
Analysis by Norviv
Money apps often make me feel as if I am being handed homework before I have even started. MoodWallet: Money Management takes a gentler route. Its focus is the emotional side of spending, which makes it interesting for anyone who wants to feel less tense around money without immediately building a detailed budget. I tried it as a finance app from Jomo Labs, and my first impression was that it is aimed at changing the moment before a purchase, not merely recording what happened afterward.
That distinction matters. Traditional budgeting tools usually ask you to define categories, enter income, set limits, and keep every figure updated. MoodWallet is more approachable if your main problem is impulsive spending, shopping stress, or the uneasy feeling that your money disappears without a clear reason. It is free to install, rated for Everyone, and its store summary presents the idea simply: spend better without requiring a conventional budget.
I would not treat it as a replacement for a bank account, tax tool, debt planner, or full household ledger. I see it more as a small daily companion for noticing the connection between mood and spending. Used that way, it can give a first-time user a manageable starting point instead of another financial system to maintain.
What to expect when you open MoodWallet
The most useful expectation to set is that this is not a spreadsheet in disguise. The app’s short description is “MoodWallet,” and that name points toward its central idea: money decisions can be influenced by how we feel. A purchase made while bored, anxious, tired, or excited can feel very different from the same purchase made calmly. The app is designed around that kind of awareness.
In practical terms, I would approach it as a reflection tool. You are not simply asking, “How much did I spend?” You are also asking, “What was happening in my head when I decided to spend?” That question can be more revealing than a long list of categories, especially when the same type of purchase keeps appearing during stressful moments.
This makes it a good fit for a first-time finance-app user who has avoided budgeting because detailed tracking feels intimidating. It can also suit someone who already knows the basics of their finances but keeps making occasional purchases they later regret. The app’s value is likely to come from repeated, honest check-ins rather than from one dramatic setup session.
My advice is to begin with one spending pattern. Do not try to understand every part of your financial life at once. Choose something concrete, such as late-night shopping, convenience purchases during workdays, or spending after a difficult conversation. Narrow observation gives you a better chance of seeing a useful connection.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
There is also a trade-off. If you want automatic bank synchronization, detailed forecasting, shared household budgets, investment analysis, or formal debt repayment schedules, a more traditional finance app will probably serve you better. MoodWallet’s appeal is its lighter emotional entry point, not its ability to replace every financial tool.
Jomo Labs has kept the app accessible enough for a broad audience: it is available for Android users on version seven or later, and the content rating is Everyone. The current release is version 2.12.0. Those details make it practical for many older devices, although the experience can still depend on the phone and operating system you use.
The app has an average rating of 4.3 from around one hundred fifty ratings, with more than forty written reviews and over ten thousand installs. I read those figures as a sign of a small but real user base rather than proof that the approach will suit everyone. The concept is specific, so its usefulness depends heavily on whether emotional spending is a problem you actually recognize in yourself.
Starting without turning the process into a chore
On the first launch, I would resist the temptation to create a perfect financial profile. A first session should answer one simple question: can this app help me pause before or after a spending decision? If the answer becomes clear through one ordinary example, you have already made meaningful progress.
Think of setup as creating a personal language for your spending. You may notice that “treating myself” sometimes means genuine enjoyment and sometimes means trying to escape a bad mood. Those two situations can produce similar transactions but deserve different attention. Recording the feeling honestly is more useful than choosing the answer that sounds financially responsible.
A practical first setup routine is to use the app at the end of a normal day rather than during a rushed shopping trip. Recall one purchase that stands out, identify the feeling around it, and write down what you hoped the purchase would do for you. Was it meant to save time, provide comfort, reward effort, solve a real problem, or simply fill a quiet moment?
This approach also answers a question many new users have: do you need to know your entire financial situation before beginning? I would say no. You can start with a single spending experience. A complete income-and-expense inventory may be necessary in a conventional budgeting app, but MoodWallet is more approachable when you use it to examine behavior first.
That does not mean accuracy is unimportant. If you record an event, try to describe the purchase and the mood as they really were. Vague notes such as “bad spending” are less helpful than “bought food delivery after a long day because cooking felt impossible.” The second version gives you something actionable without judging you.
I also recommend choosing a regular moment for checking in. It could be after dinner, before bed, or immediately after a purchase that feels unusually emotional. The exact routine matters less than keeping it small enough to continue. A finance app becomes useful when it fits into life; it becomes a burden when every entry feels like an accounting session.
The first meaningful success is a pause, not a perfect budget
For a first-time user, the first successful action should be modest: identify one emotional trigger and make one different choice the next time it appears. That might mean waiting before buying, choosing a cheaper alternative, removing a tempting item from a cart, or deciding that the purchase is worthwhile and making it without guilt. The point is not always to spend less. The point is to spend deliberately.
Here is a realistic scenario. Imagine I have had a frustrating workday and open a shopping app while sitting on the sofa. I notice the urge to buy several small items that were not part of my plan. Instead of treating the urge as a command, I use MoodWallet’s central idea as a prompt: what am I feeling, and what do I expect this purchase to change? If the honest answer is “I want a quick lift,” I can pause and decide whether the item is worth the cost or whether another form of recovery would help more.
That pause is the meaningful result. Even when I still buy the item, I have learned something about the decision. If the same pattern appears repeatedly, I can prepare for it: keep a low-cost comfort option available, avoid browsing when exhausted, or set a short waiting period before nonessential purchases.
A less obvious use is reviewing positive spending, not only regretted spending. A meal with friends, a hobby purchase, or a convenience expense can be emotionally healthy and still deserve attention. If you label every enjoyable purchase as a failure, the app may reinforce shame rather than improve judgment. I found it more useful to separate “this helped me” from “this was an automatic reaction.” That distinction protects the parts of spending that genuinely support your life.
Another useful workflow is to compare intention with outcome. Before a purchase, you may expect it to reduce stress for the evening. Later, you can consider whether it actually did. Over time, this can reveal which purchases deliver lasting value and which only provide a short burst of relief. That is a stronger insight than simply seeing a category total.
The app is also potentially useful for people who share financial decisions with a partner, although I would use it carefully. Instead of presenting a list of blameworthy purchases, you could discuss recurring emotional triggers as a household pattern. “We spend more when we are rushed” leads to a practical conversation about planning meals or errands. “You always waste money” usually leads nowhere.
Where new users may feel confused
The biggest possible confusion is expecting MoodWallet to behave like a conventional budget manager. If you open it looking for a complete financial dashboard, you may wonder why emotional context is receiving so much attention. That is not a missing version of a standard budgeting tool; it is the reason this app exists. Approach it as a way to understand spending decisions, and its design makes more sense.
Another point worth clarifying is that reflection is not the same as financial control. The app can help you notice patterns, but noticing a pattern does not automatically change it. You still need to decide what action follows. For example, recognizing stress spending is useful, but the practical improvement might require changing your evening routine, setting a purchase delay, or discussing pressure at work.
Some users may also be unsure whether they should record every purchase. I would not begin that way unless detailed tracking is already comfortable for you. Start with emotionally noticeable purchases, repeated problem areas, or decisions that surprised you. Once the habit feels natural, you can broaden it if doing so adds clarity rather than noise.
There is a subtle danger in turning mood labels into excuses. “I was anxious” should explain a decision, not automatically justify it. The better question is what you want to do with that information next time. MoodWallet works best when the emotional note leads to a small experiment rather than a permanent label about your personality.
Privacy-minded users should make their own comfort assessment before entering sensitive personal reflections. Financial and emotional notes can be intimate. I would avoid writing details that you would not want stored in an app, and I would keep the entries focused on practical patterns. That is sensible for any finance tool, especially one that combines spending with feelings.
There is also a cost consideration. The app is free, but it includes in-app purchases ranging from $6.99 to $89.99 per item. Before paying for anything, I would use the free experience long enough to decide whether the method changes your behavior. A paid option is only worthwhile if it supports a routine you are genuinely using; no upgrade can substitute for consistent reflection.
How it compares with ordinary budgeting alternatives
A spreadsheet gives you control, flexibility, and transparency, but it expects you to design the system and keep it updated. A bank’s built-in spending view may be convenient for seeing transactions, yet it usually tells you what happened rather than why you made the choice. A strict envelope-style budget is stronger when you need firm limits for bills, savings, or debt.
MoodWallet occupies a different position. It is most useful before a spending pattern becomes a serious budget problem, or alongside a traditional tool when the numbers alone are not explaining your behavior. You might use a bank app for balances and payments, a spreadsheet for monthly planning, and MoodWallet for the emotional triggers that cause you to ignore the plan.
The trade-off is precision. A detailed budget can tell you exactly how much remains in a category. Mood-based reflection can tell you why you keep exceeding that category, but it may not provide the same immediate guardrail. If your rent, bills, or debt payments are at risk, choose a tool with explicit planning and alerts first. MoodWallet is better suited to the behavioral layer around those obligations.
It is also less suitable for someone who enjoys numbers and wants advanced analysis. If charts, projections, account imports, and granular reports motivate you, a full finance manager will likely feel more satisfying. If those features make you abandon money tracking altogether, the simpler emotional approach may be the better starting point.
Who should try it and who should move on
I would recommend MoodWallet to someone who says, “I know what I should do with money, but I keep spending differently when I am stressed, bored, lonely, or tired.” It is also a reasonable choice for a beginner who wants a low-pressure first step and does not want to build a budget before understanding personal habits.
It can be especially useful after a spending regret. Instead of deleting the evidence or promising never to do it again, you can examine the moment with curiosity. What happened immediately beforehand? What did you want the purchase to solve? What would make the next version of that situation easier? Those questions turn regret into a small plan.
I would skip it as a primary tool if you need a shared household budget, formal bill scheduling, investment tracking, business bookkeeping, or detailed debt calculations. I would also skip it if you dislike reflecting on emotions and only want automatic transaction categorization. In those cases, the app’s defining strength may feel like unnecessary work.
People dealing with serious financial hardship should be cautious about relying on reflection alone. Emotional awareness can help, but urgent problems may require a concrete spending plan, professional advice, creditor communication, or support from a trusted person. This app can complement those steps, not replace them.
A simple path from installation to a useful routine
My suggested first week is intentionally small. On the first day, record one purchase that carried an obvious feeling. On the next few days, notice whether the same feeling appears before spending, even when you do not buy anything. Then choose one trigger and test one response, such as waiting, substituting, preparing in advance, or deciding to spend with intention.
At the end of that period, look for a pattern rather than a score. You are trying to learn whether particular situations change your decisions. If the pattern is clear, keep the routine. If it is not, try a different type of purchase or a different time of day. The goal is not to produce a perfect record; it is to make one money decision more conscious.
One advanced tip is to separate emotional intensity from purchase value. A low-cost purchase can still reveal a strong trigger, while an expensive purchase can be entirely planned and worthwhile. If you focus only on price, you may miss the behavior MoodWallet is best at exposing. Ask how powerful the feeling was and whether the purchase matched your real priorities.
Another is to review successful pauses. When you wanted something but chose to wait, record what made that possible. Perhaps you were rested, had eaten, had a clear reason for saving, or simply gave yourself ten minutes. Those conditions are practical tools. Repeating them is often more effective than relying on willpower.
My final view is that MoodWallet: Money Management is a focused finance app with a humane idea behind it. It does not try to win by making money management more complicated. Instead, it invites you to examine the emotional moment where many spending decisions begin. That will not satisfy everyone, and its free installation does not mean every useful financial function is covered without optional purchases.
Still, for a first-time user who feels overwhelmed by budgeting, the app offers a reassuring route to a first success: notice one pattern, pause once, and make one choice with clearer intent. I would use it alongside a more traditional tool when precise financial control is needed, but I would recommend giving it a fair trial if emotional spending is the part of money management you have never been able to explain.
Frequently Asked Questions
01What is MoodWallet: Money Management, and who is it designed for?
MoodWallet: Money Management is a personal finance app designed to help users monitor spending, organize expenses, and develop better financial habits. Its approach may be especially useful for people who want a simple overview of their money without using complex spreadsheets. It can suit beginners, students, families, or anyone looking for a convenient way to review daily transactions and understand where their money is going.
02How does MoodWallet help users track their spending and budget?
The app is intended to make expense tracking more manageable by allowing users to record financial activity and categorize purchases. Once transactions are entered, users can review spending patterns and compare them with their personal budget goals. This can make recurring expenses, unnecessary purchases, and areas requiring adjustment easier to identify. The quality of the results depends on keeping the information accurate and up to date.
03Does MoodWallet connect directly to bank accounts or require manual entry?
Before downloading, users should check the current version’s connection options because financial apps can differ by country, bank, and platform. MoodWallet may rely on manually entered transactions or offer supported account integrations, depending on its latest features. Manual tracking provides more control but requires consistency, while automatic synchronization can save time. Always review permissions and supported institutions before linking any financial account.
04Is MoodWallet: Money Management safe to use for personal financial information?
Users should carefully review MoodWallet’s privacy policy, permissions, and data-handling practices before entering sensitive information. Avoid sharing passwords, banking credentials, or personal details unless the app clearly explains how they are protected. It is also wise to use a strong device passcode, keep the application updated, and download it only from an official store. The app should be treated as a budgeting tool, not a replacement for secure banking services.
05Is MoodWallet free, and are there in-app purchases or premium features?
The available features, advertisements, subscription plans, and in-app purchases may vary according to the operating system and the app version. Users should check the official Google Play or App Store listing for the current pricing details before installing. If a premium option exists, compare its benefits with the free tools first. Also review renewal terms carefully, particularly for subscriptions that may continue charging until canceled through the relevant store settings.


